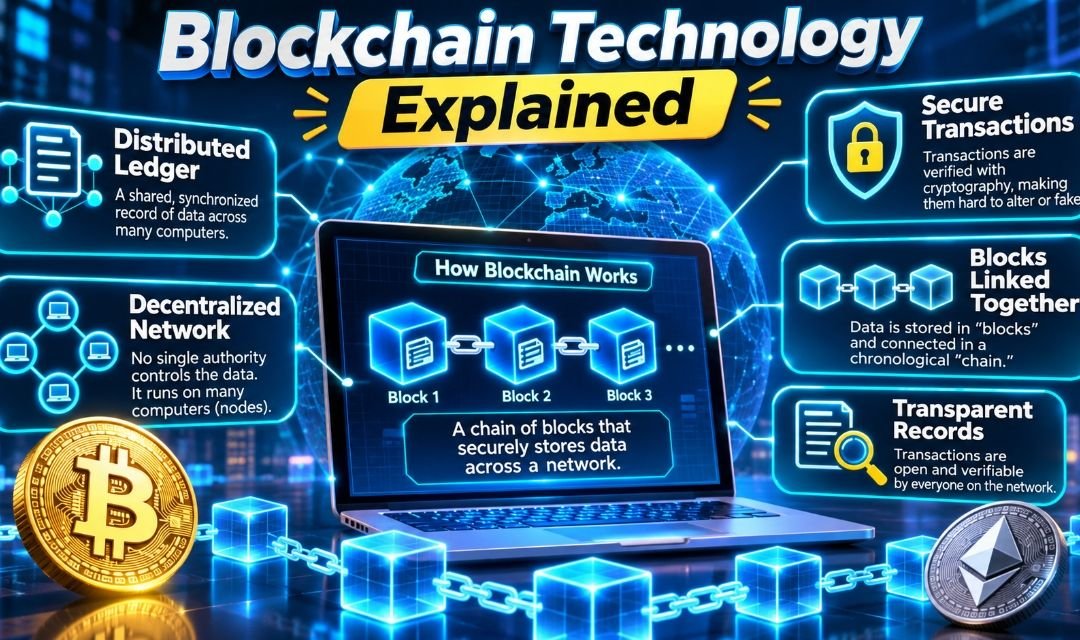
Blockchain technology explained in simple words means understanding how digital information can be recorded, shared, and verified across a network of computers without always depending on one central authority. Blockchain is the technology behind cryptocurrencies such as Bitcoin and Ethereum, but its potential uses extend beyond digital money. A blockchain is a digital ledger that stores information in connected blocks, using cryptography and network rules to make recorded transactions difficult to change without detection. Today, blockchain technology is being explored in finance, supply chains, digital identity, healthcare, and many other industries.
Quick Overview of Blockchain Technology
| Category | Details |
|---|---|
| Technology name | Blockchain |
| Main purpose | Recording and verifying digital information |
| Popular applications | Bitcoin, Ethereum, digital payments |
| First major cryptocurrency application | Bitcoin, launched in 2009 |
| Core structure | Connected blocks of data |
| Main technology | Cryptography and distributed ledgers |
| Network models | Public, private, consortium |
| Consensus methods | Proof of Work, Proof of Stake |
| Important features | Transparency, verification, tamper resistance |
| Common uses | Finance, supply chains, digital identity |
| Smart contract platform | Ethereum |
| Main challenges | Scalability, privacy, security, regulation |
Blockchain technology has become an important subject in the digital world.
Many people first hear about blockchain through Bitcoin.
However, blockchain and cryptocurrency are not the same thing.
Cryptocurrency is one application of blockchain technology.
Blockchain itself is a method of organizing and verifying digital records.
It allows multiple participants to maintain a shared history of transactions.
Instead of relying entirely on one organization to manage a database, some blockchain networks distribute recordkeeping across many computers.
However, not every blockchain is fully decentralized.
Some networks are operated by a limited number of organizations.
Understanding these differences helps explain why blockchain is useful, where it faces challenges, and how it may develop in the future.
What Is Blockchain Technology?
Blockchain is a type of digital ledger.
A ledger is a record of transactions or other information.
Traditional ledgers may be managed by a bank, company, or government organization.
Blockchain networks use cryptographic techniques and agreed rules to maintain records.
Information is organized into blocks.
Each block contains data and a cryptographic reference to an earlier block.
These references connect the blocks into a chain.
Changing an older block would affect the cryptographic links to later blocks.
However, blockchain records are not absolutely impossible to change.
Their resistance to modification depends on the network design, consensus mechanism, and control of the participating computers.
How Does Blockchain Technology Work?
Blockchain technology works through a series of connected processes.
The exact steps differ between networks.
However, many blockchains follow a similar general structure.
Step 1: A Transaction Is Created
A user requests a transaction.
For example, someone may want to send Bitcoin to another wallet.
The transaction contains information needed by the network.
This may include the destination, amount, and cryptographic authorization.
Step 2: The Transaction Is Shared
The transaction is broadcast to participating network computers.
These computers are commonly called nodes.
Nodes help maintain and verify blockchain information.
However, their responsibilities vary depending on the network.
Step 3: The Transaction Is Checked
Network participants verify whether the transaction follows the required rules.
For cryptocurrency transfers, this may include checking digital signatures and available funds.
Invalid transactions should be rejected by correctly operating nodes.
Step 4: Transactions Are Grouped
Valid transactions may be collected into a block.
The process differs between blockchain systems.
Some networks use miners.
Others use validators.
Step 5: The Network Reaches Consensus
The blockchain uses a consensus mechanism to determine which records should be accepted.
Bitcoin uses Proof of Work.
Ethereum uses Proof of Stake.
These systems operate differently.
Step 6: The Block Is Added
Once accepted according to the network’s rules, the new block becomes part of the blockchain history.
Step 7: The Ledger Is Updated
Participating nodes update their records.
However, transaction finality differs between networks.
Some transactions may require additional confirmations before users consider them sufficiently settled.
What Is a Block in Blockchain?
A block is a structured collection of information.
In cryptocurrency networks, blocks commonly contain transaction records.
They also include information that helps connect them to previous blocks.
A simplified block may contain the following elements.
| Block component | Purpose |
|---|---|
| Transaction data | Records relevant transactions |
| Previous block hash | Links the block to earlier history |
| Timestamp or time information | Provides network-related timing data |
| Cryptographic information | Supports verification |
| Consensus-related data | Helps the network accept the block |
The exact structure depends on the blockchain.
Not every blockchain uses identical block fields.
What Is a Blockchain Hash?
A cryptographic hash is the output of a mathematical function.
It converts input data into a fixed-length result for a particular hashing algorithm.
Even a small change to the input typically produces a very different output.
Blockchains use hashes for important verification tasks.
For example, hashes can help connect blocks and identify changes to recorded information.
However, a hash is not the same as encryption.
Hashing and encryption serve different purposes.
What Is Decentralization in Blockchain?
Decentralization means that control or responsibility is distributed rather than concentrated entirely in one place.
In some blockchain networks, many independent participants maintain copies of the ledger.
This can reduce dependence on a single organization.
However, decentralization is not an all-or-nothing feature.
Some networks have many independent validators.
Others rely on a small group of approved participants.
A network may also become concentrated if a few organizations control much of its computing power or validation activity.
Therefore, the actual level of decentralization depends on how the network operates.
What Is a Distributed Ledger?
A distributed ledger is a shared record maintained across multiple computers or organizations.
Blockchain is one form of distributed ledger technology.
However, not every distributed ledger uses blocks linked into a chain.
Some distributed ledger systems use different data structures.
The main idea is that multiple participants can maintain and verify shared information according to agreed rules.
Types of Blockchain Technology
Blockchain networks can be organized in different ways.
1. Public Blockchain
A public blockchain generally allows broad participation.
Examples include Bitcoin and Ethereum.
People can usually inspect transaction records and interact with the network without receiving permission from one central operator.
However, participating as a validator may involve additional technical or economic requirements.
Advantages: Open participation, transparency, and reduced reliance on one operator.
Disadvantages: Privacy limitations, transaction costs, and possible congestion.
2. Private Blockchain
A private blockchain restricts participation.
A company or organization may control who can access the network.
Private blockchains may be used for internal business processes.
However, they do not provide the same decentralization properties as open public networks.
Advantages: Greater control over access and governance.
Disadvantages: More dependence on the controlling organization.
3. Consortium Blockchain
A consortium blockchain is managed by a group of organizations.
For example, several businesses may share responsibility for maintaining a ledger.
This can support cooperation between organizations.
However, participants must agree on governance and technical standards.
4. Hybrid Blockchain
A hybrid blockchain combines elements of public and restricted systems.
Some information may be publicly verifiable.
Other information may remain accessible only to authorized participants.
However, the exact design varies between implementations.
Public vs Private Blockchain Comparison
| Feature | Public blockchain | Private blockchain |
|---|---|---|
| Participation | Generally open | Restricted |
| Governance | Distributed according to network rules | Controlled by approved parties |
| Transparency | Often publicly auditable | Depends on access permissions |
| Privacy | Public records may reveal activity | More control over data access |
| Examples | Bitcoin, Ethereum | Enterprise permissioned networks |
| Main challenge | Scalability and public data exposure | Trust and centralization |
What Is Proof of Work?
Proof of Work is a blockchain consensus mechanism.
Bitcoin uses Proof of Work to secure its network.
Miners compete to solve a computational challenge.
The successful miner proposes a block according to the network’s rules.
Other nodes independently verify the block.
Proof of Work makes rewriting blockchain history costly under normal security assumptions.
However, it requires substantial computing resources and electricity.
It is not immune to every possible attack.
What Is Proof of Stake?
Proof of Stake is another consensus approach.
Ethereum uses Proof of Stake.
Validators commit cryptocurrency as stake to participate in securing the network.
They may receive rewards for following protocol rules.
However, dishonest behavior can result in penalties.
Proof of Stake generally requires much less energy than Proof of Work.
Nevertheless, it introduces different security, governance, and economic considerations.
Proof of Work vs Proof of Stake
| Feature | Proof of Work | Proof of Stake |
|---|---|---|
| Main resource | Computing power | Staked assets |
| Participants | Miners | Validators |
| Well-known example | Bitcoin | Ethereum |
| Energy demand | Generally higher | Generally lower |
| Security model | Cost of computation | Economic stake and penalties |
| Main concern | Mining concentration and energy use | Stake concentration and validator governance |
Neither method guarantees perfect security.
What Are Smart Contracts?
Smart contracts are programs that execute according to rules defined in their code.
They can run on supported blockchain networks.
Ethereum is a well-known smart contract platform.
For example, a smart contract may manage token transfers when specified conditions are satisfied.
However, smart contracts are not automatically legally enforceable contracts.
They are computer programs.
Coding errors and malicious designs can lead to financial losses.
Therefore, smart contract security is a major concern in blockchain applications.
What Is Ethereum Blockchain?
Ethereum is a blockchain platform that supports smart contracts and decentralized applications.
It launched in 2015.
Its native cryptocurrency is Ether, commonly called ETH.
Ethereum uses Proof of Stake.
Developers can build applications that operate through Ethereum-compatible smart contracts.
However, using Ethereum can involve transaction fees and technical complexity.
Network congestion may also affect transaction costs.
What Is Bitcoin Blockchain?
Bitcoin is a decentralized digital currency network introduced in 2009.
Its blockchain records Bitcoin transactions.
Bitcoin uses Proof of Work.
The network is designed to allow participants to transfer Bitcoin without requiring a traditional bank to maintain the central ledger.
However, Bitcoin transactions can involve fees and confirmation delays.
Bitcoin prices are also highly volatile.
Blockchain security does not guarantee cryptocurrency price stability.
Blockchain vs Cryptocurrency
Blockchain and cryptocurrency are related but different.
Blockchain is the underlying recordkeeping technology.
Cryptocurrency is a type of digital asset that may operate through blockchain networks.
| Feature | Blockchain | Cryptocurrency |
|---|---|---|
| Definition | Distributed recordkeeping technology | Digital asset |
| Main purpose | Record and verify information | Transfer or represent digital value |
| Examples | Bitcoin blockchain, Ethereum blockchain | BTC, ETH |
| Can exist independently? | Yes | Many cryptocurrencies depend on blockchains |
| Main risks | Security, governance, scalability | Volatility, custody, scams |
A blockchain can support applications that do not require a publicly traded cryptocurrency.
Benefits of Blockchain Technology
1. Shared Recordkeeping
Blockchain can allow multiple participants to maintain a common record.
This may reduce disagreements about transaction history.
2. Transparency
Public blockchains allow people to inspect recorded transactions.
However, transparency does not mean every user is personally identifiable.
3. Tamper Resistance
Cryptographic links and consensus mechanisms can make unauthorized historical changes difficult.
However, the strength of this protection depends on network design.
4. Reduced Dependence on Intermediaries
Some blockchain applications allow participants to interact without a traditional central recordkeeper.
However, many real-world services still depend on exchanges, developers, and other intermediaries.
5. Programmability
Smart contracts allow developers to automate certain digital processes.
However, software errors can create significant risks.
6. Global Network Access
Public blockchain networks may be accessible across national borders.
However, internet access, regulations, and platform restrictions can limit participation.
Disadvantages of Blockchain Technology
Blockchain also has important limitations.
Scalability
Some networks process fewer transactions than centralized payment systems.
Congestion can increase costs or delays.
Energy Consumption
Proof of Work networks may require substantial electricity.
However, energy demand varies greatly between blockchain designs.
Privacy
Public transaction records can reveal financial activity.
Even when addresses are pseudonymous, activity may sometimes be linked to real identities.
Security Risks
Blockchain applications can suffer from software vulnerabilities, stolen private keys, and malicious transactions.
Regulation
Different countries apply different rules to cryptocurrency and blockchain-related services.
Complexity
Blockchain systems can be difficult for beginners and organizations to understand.
Irreversible Transactions
Many blockchain transactions cannot be reversed after final settlement.
Mistakes may cause permanent losses.
Real-World Applications of Blockchain Technology
Blockchain technology has potential uses beyond cryptocurrency.
However, the practical benefits depend on whether a shared ledger is actually needed.
1. Banking and Financial Services
Blockchain-based systems can support digital asset transfers and settlement processes.
Some financial institutions are exploring tokenized assets.
However, regulatory and technical challenges remain.
2. International Payments
Blockchain networks may help transfer digital value across borders.
However, conversion fees, liquidity, and local regulations can affect costs.
3. Supply Chain Management
Blockchain can record information about products moving through supply chains.
For example, participants may track shipping events or ownership transfers.
However, blockchain cannot automatically verify that information entered into the system is accurate.
4. Healthcare
Blockchain systems are being explored for record verification and data-sharing processes.
However, sensitive medical information requires strong privacy protections.
Storing confidential patient data directly on a public blockchain can create serious problems.
5. Digital Identity
Blockchain-based systems may help manage certain digital credentials.
However, identity verification still depends on trustworthy organizations and processes.
6. Real Estate
Blockchain can support digital records related to property transactions.
However, legal ownership depends on applicable laws and official registration systems.
7. Education
Educational institutions may use cryptographic verification to help authenticate certificates.
However, blockchain is not always necessary for this purpose.
8. Insurance
Smart contracts may automate selected insurance processes.
However, real-world claims often require external evidence and human review.
9. Gaming
Some games use blockchain to represent digital items.
However, ownership of a blockchain token does not necessarily grant copyright or unrestricted use of the associated content.
10. Digital Art and NFTs
Non-fungible tokens can represent unique blockchain records.
However, owning an NFT does not automatically mean owning the underlying artwork’s copyright.
Blockchain Technology in Banking
Banks and financial institutions are exploring distributed ledger systems for certain operations.
Potential applications include settlement, tokenized deposits, and shared financial records.
However, blockchain is not automatically faster or cheaper than existing banking systems.
The benefits depend on transaction volume, governance, infrastructure, and regulatory requirements.
Some projects may be better served by conventional databases.
Blockchain Technology in Supply Chain Management
Supply chains involve manufacturers, shipping companies, distributors, and retailers.
A shared ledger may help these organizations coordinate records.
For example, participants could record when goods move between locations.
However, blockchain cannot guarantee that a physical product matches its digital record.
Accurate tracking still requires reliable data collection and verification.
Blockchain Technology in Healthcare
Healthcare organizations manage sensitive information.
Blockchain may support verification of access records or document integrity.
However, public blockchain transparency can conflict with patient privacy requirements.
Sensitive medical records should not simply be placed on an immutable public ledger.
Practical systems require careful privacy engineering, governance, and legal compliance.
What Is Blockchain Scalability?
Scalability refers to a network’s ability to handle increasing activity.
Some blockchain networks face limits on transaction throughput.
When demand increases, transaction fees may rise.
Confirmation times may also become less predictable.
Developers use different methods to address scalability.
These include protocol improvements and additional processing layers.
However, scalability improvements can involve tradeoffs involving security and decentralization.
What Are Layer 1 and Layer 2 Blockchains?
Layer 1 refers to a blockchain’s main network.
Bitcoin and Ethereum are examples of Layer 1 networks.
Layer 2 systems operate alongside or above an underlying blockchain to improve certain capabilities.
Some Ethereum Layer 2 systems process transactions and submit data or proofs to Ethereum.
However, Layer 2 designs differ.
Users should understand withdrawal rules, security assumptions, and operational risks.
What Is Blockchain Interoperability?
Interoperability refers to the ability of different blockchain networks or systems to communicate.
For example, users may want to transfer information or assets between networks.
However, blockchain bridges can introduce security risks.
Some bridge systems depend on smart contracts or external operators.
A vulnerability may result in significant asset losses.
Therefore, interoperability remains an important technical challenge.
What Is Blockchain Tokenization?
Tokenization involves representing an asset or claim through a digital token.
For example, a token might represent a financial instrument or another contractual right.
However, the token’s legal meaning depends on the arrangement behind it.
Owning a token does not automatically establish ownership of a physical asset.
Legal documentation, custody, and enforcement remain important.
Is Blockchain Technology Secure?
Blockchain security depends on several factors.
These include cryptography, consensus rules, network participation, software quality, and governance.
Large established networks may be difficult to attack through certain methods.
However, blockchain systems can still experience vulnerabilities.
Private keys can be stolen.
Smart contracts can contain errors.
Applications can be compromised.
Users may also be deceived into authorizing harmful transactions.
Therefore, blockchain should not be described as completely hack-proof.
Blockchain Technology vs Traditional Databases
Traditional databases and blockchains both store information.
However, they serve different needs.
| Feature | Blockchain | Traditional database |
|---|---|---|
| Record management | Shared according to network rules | Usually controlled by an administrator |
| Data modification | Often restricted or historically traceable | Usually easier for authorized administrators |
| Performance | May involve consensus overhead | Often optimized for high performance |
| Transparency | Can be publicly auditable | Depends on access controls |
| Governance | May involve multiple parties | Usually centralized |
| Best use | Shared records among parties with limited mutual trust | Conventional organizational data management |
Blockchain is not automatically better than a traditional database.
The appropriate choice depends on the problem being solved.
Future of Blockchain Technology in 2026 and Beyond
Blockchain development continues across several areas.
However, future adoption remains uncertain.
More Scalable Networks
Developers are exploring ways to increase transaction capacity.
Better Wallet Security
Wallet designs are evolving to improve recovery and transaction verification.
Tokenized Financial Assets
Financial organizations are experimenting with blockchain representations of certain assets.
Privacy Technologies
Cryptographic techniques may help verify information without exposing all underlying data.
Improved Interoperability
Developers continue working on communication between blockchain networks.
Enterprise Applications
Organizations are evaluating whether distributed ledgers improve specific business processes.
However, not every experiment will become commercially successful.
Blockchain adoption depends on real benefits, economic costs, security, and regulation.
How to Learn Blockchain Technology for Beginners
Beginners can learn blockchain without buying cryptocurrency.
A useful learning approach includes studying the following subjects.
| Week | Learning topic | Activity |
|---|---|---|
| Week 1 | Blockchain basics | Understand blocks and ledgers |
| Week 2 | Cryptography | Learn hashes and digital signatures |
| Week 3 | Bitcoin | Study Proof of Work |
| Week 4 | Ethereum | Learn Proof of Stake |
| Week 5 | Wallets | Understand public and private keys |
| Week 6 | Smart contracts | Study automated blockchain programs |
| Week 7 | Security | Learn about phishing and software risks |
| Week 8 | Applications | Compare blockchain with databases |
This learning plan is educational and does not require financial investment.
Common Blockchain Technology Myths
Myth 1: Blockchain and Bitcoin Are the Same
Bitcoin is one application of blockchain technology.
Myth 2: Blockchain Cannot Be Hacked
Blockchain networks and related applications can experience security failures.
Myth 3: Every Blockchain Is Decentralized
Some blockchain networks are controlled by a limited group of participants.
Myth 4: Blockchain Is Always Faster
Traditional databases may be faster for many applications.
Myth 5: Blockchain Guarantees Privacy
Public blockchains may expose transaction information.
Myth 6: Every Business Needs Blockchain
Many business problems can be solved more simply with conventional technology.
Final Thoughts
Blockchain technology explained in simple terms is the study of how digital information can be recorded, verified, and shared through connected cryptographic records.
Bitcoin introduced blockchain to a global audience.
Ethereum expanded its use through smart contracts and decentralized applications.
Today, blockchain technology is being explored in finance, supply chains, digital identity, and other industries.
However, blockchain is not a perfect solution for every problem.
Scalability, privacy, security, and regulation remain important challenges.
Traditional databases may be more practical for many applications.
For beginners, understanding blocks, hashes, consensus mechanisms, private keys, and smart contracts provides a useful foundation.
The future of blockchain will depend on whether its real-world applications deliver meaningful benefits.
Frequently Asked Questions About Blockchain Technology
1. What is blockchain technology in simple words?
Blockchain is a digital recordkeeping system that connects blocks of information using cryptographic methods.
2. How does blockchain work?
Transactions are verified according to network rules and recorded in connected blocks.
3. Who invented blockchain?
The ideas behind blockchain developed over time. Bitcoin’s blockchain was introduced through the work published under the name Satoshi Nakamoto in 2008.
4. Is blockchain the same as Bitcoin?
No. Bitcoin is a cryptocurrency that uses blockchain technology.
5. What is a block in blockchain?
A block is a structured collection of records connected to previous blockchain history.
6. What is a blockchain node?
A node is a computer participating in a blockchain network.
7. What is blockchain mining?
Mining is the process used by Proof of Work networks to compete for the right to propose blocks.
8. What is Proof of Work?
It is a consensus mechanism based on computational work.
9. What is Proof of Stake?
It is a consensus approach that uses staked assets and validators.
10. What is a smart contract?
A smart contract is a program that executes according to defined rules on a supported blockchain.
11. Is blockchain secure?
Blockchain can provide strong security properties, but no implementation is completely risk-free.
12. Can blockchain records be changed?
Changing accepted records can be difficult, but the degree of resistance depends on the network.
13. What is a public blockchain?
A public blockchain generally allows broad participation and verification.
14. What is a private blockchain?
A private blockchain restricts participation to approved users or organizations.
15. What is a distributed ledger?
It is a shared record maintained across multiple participants or systems.
16. What is Ethereum?
Ethereum is a blockchain platform that supports smart contracts and decentralized applications.
17. What is blockchain tokenization?
Tokenization involves representing assets or claims through digital tokens.
18. What is Layer 2 blockchain technology?
Layer 2 refers to systems designed to provide additional capabilities while relying on an underlying blockchain in specified ways.
19. Can blockchain be used without cryptocurrency?
Yes. Some blockchain systems operate without publicly traded cryptocurrencies.
20. Is blockchain useful in banking?
It may support selected financial processes, but its benefits depend on implementation.
21. Can blockchain improve supply chains?
It may improve shared recordkeeping, but it cannot automatically verify physical goods.
22. Is blockchain completely anonymous?
No. Many public blockchains are pseudonymous rather than fully anonymous.
23. Does blockchain use a lot of electricity?
Energy consumption varies. Proof of Work generally uses more energy than Proof of Stake.
24. Can beginners learn blockchain for free?
Yes. Blockchain concepts can be studied without purchasing cryptocurrency.
25. What is the future of blockchain technology?
Future developments may include scalability improvements, tokenization, privacy technologies, and specialized business applications.
For more cryptocurrency education, Bitcoin guides, blockchain tutorials, and beginner-friendly technology articles, visit Picanto Magazine